Spain’s Ministry of Finance has postponed the enforcement of obligations under the Billing Computer Systems Regulation (SIF) to October 2028. The decision aims to align requirements with the mandatory B2B e-invoicing timeline while anticipating future digital reporting demands under the EU’s ViDA directive. While this extension offers businesses welcome breathing room, it should not be taken as a signal to halt digital transformation efforts.
1. Spain Defers SIF Implementation to October 2028
The Ministry of Finance has officially adjusted the implementation schedule for the Billing Computer Systems Regulation (Real Decreto 1007/2023).
Originally slated for 2027, the mandatory technical compliance deadlines for software systems supporting invoicing workflows have now been pushed back to October 2028.
This adjustment synchronizes SIF compliance with the rollout of mandatory B2B electronic invoicing across small businesses and self-employed professionals, preventing companies from having to undergo fragmented technology transitions in close succession.
Key Distinction: The Billing Computer Systems Regulation (SIF) defines the core integrity and anti-fraud specifications for invoicing software, whereas Veri*factu represents a specific optional mode for real-time automated record transmission to the Spanish Tax Agency (AEAT).
2. What Is Driving This Schedule Adjustment?
This extension goes beyond administrative delays. It reflects a strategic effort to achieve technical and regulatory convergence across fiscal reporting frameworks:
Regulatory Synchronization: Preventing enterprises from making multiple, disconnected software upgrades over a short timeframe.
Alignment with EU ViDA (VAT in the Digital Age): Preparing Spanish business software architectures for upcoming European digital reporting requirements scheduled from 2030 onwards.
Cost & Efficiency Optimization: Responding to industry feedback from tax advisors and financial intermediaries to ensure an orderly transition toward a unified model.
In short, the objective is to build a more connected, streamlined reporting ecosystem.
3. What Changes and What Remains Intact?
While the implementation timeline has shifted, the underlying objective—modernizing corporate invoicing infrastructure—remains unchanged.
The technical guarantees and requirements established by the SIF regulation remain substantially equivalent:
Integrity and immutability of billing records.
Traceability, accessibility, legibility, and preservation of data.
Standardized data structures for seamless record processing.
System guarantees ensuring compliant generation and handling of financial operations.
Technical specifications will be refined during this transitional period to ensure seamless interoperability between e-invoicing platforms and tax reporting systems.
4. Strategic Outlook: Transitioning to an Integrated Reporting Model
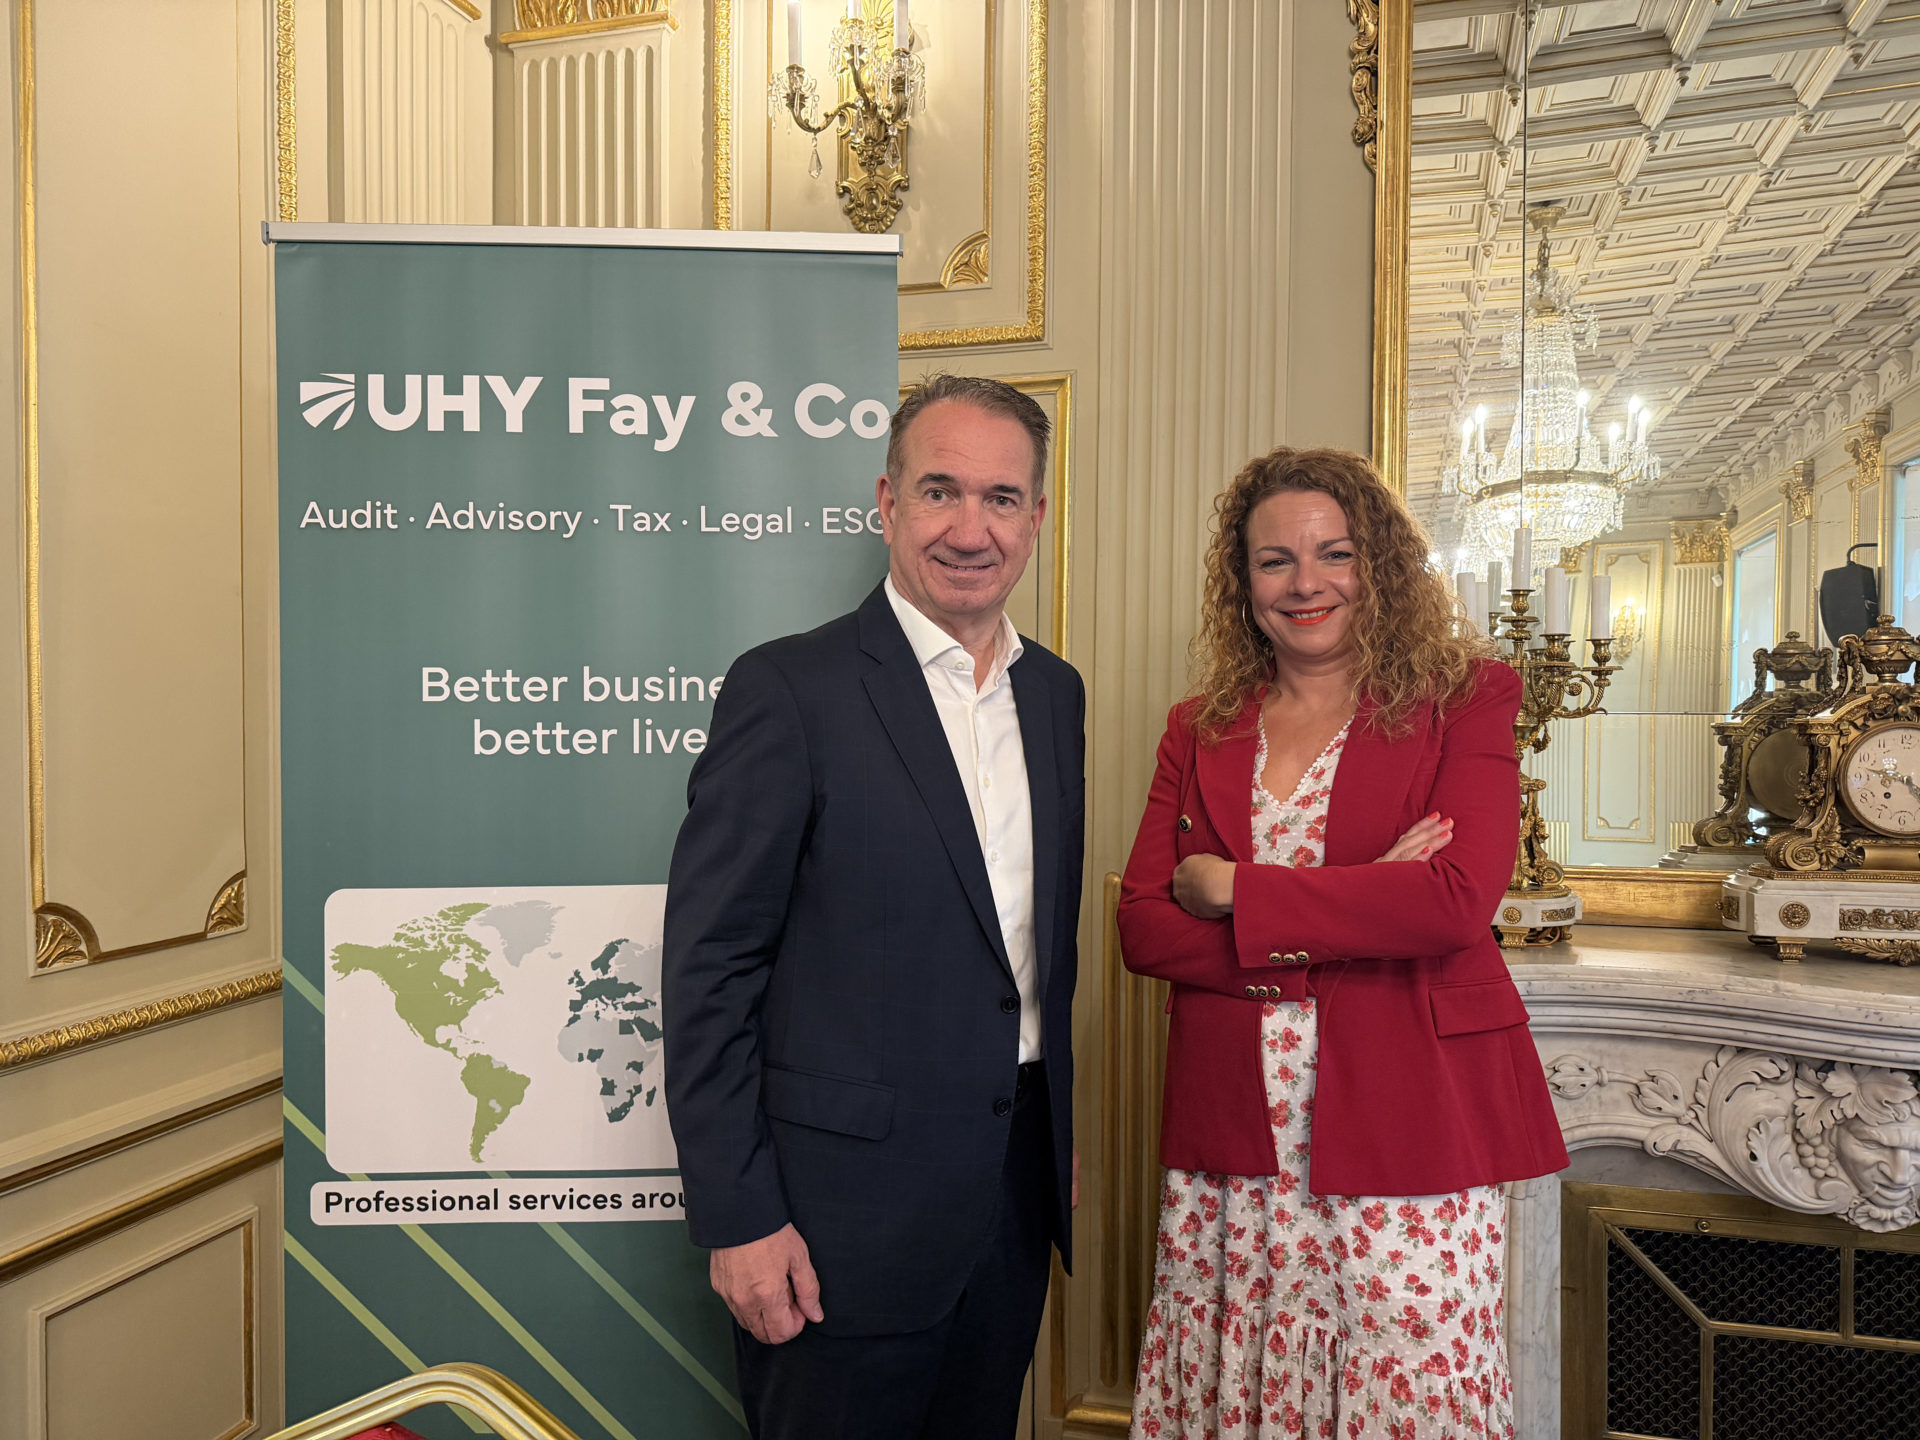
As highlighted by Minerva Cristóbal Casado, Head of Business Services & Outsourcing at UHY Fay & Co:
“The key takeaway here is not ‘we have two extra years,’ but rather ‘the entire invoicing and tax reporting model is undergoing a structural shift.’ Companies must prepare for the complete ecosystem, rather than focusing on an isolated compliance task.”
Treating this deferral as a reason to pause modernization would be a strategic misstep.
Businesses that delay upgrading their financial technology until the deadline will likely face higher integration costs, operational bottlenecks, and implementation risks when mandatory e-invoicing and digital reporting take effect simultaneously.
The extension should be viewed as an opportunity to review existing architectures and proactively build for future standards.
5. Practical Steps for Business Preparation
Compliance should extend beyond verifying software technical checks. Organizations should use this window to review their overarching financial data architecture:
Audit Current Systems: Confirm whether existing ERPs or accounting software can scale to meet future digital reporting requirements.
Review Invoicing Workflows: Analyze invoice generation, transaction logging, credit notes, and error-handling workflows.
Assess System Interoperability: Ensure seamless data flow between invoicing platforms, accounting ledgers, VAT registers, and tax filings.
Plan Automation: Identify manual tasks that can be automated to reduce duplication and compliance risks.
Adopt an Integrated Vision: Address mandatory B2B e-invoicing, SIF regulations, and EU digital reporting standards holistically.
Frequently Asked Questions
When do the Spanish Billing Computer Systems (SIF) regulations take effect?
The enforcement of pending SIF obligations has been deferred to October 2028, coinciding with mandatory B2B e-invoicing for companies and professionals with annual revenues under €8 million.
What is the difference between SIF, Veri*factu, and B2B Electronic Invoicing in Spain?
SIF Regulations (RD 1007/2023): Dictates the integrity, security, and anti-fraud technical requirements that billing software must meet.
Veri*factu: A voluntary compliance mode within SIF where software automatically submits billing records directly to the Tax Agency in real time.
Electronic Invoicing: Regulates the issuance, transmission, and reception of structured electronic invoices between businesses under Spain’s Crea y Crece Law.
While distinct, these frameworks represent complementary pillars of Spain’s broader tax digitalization strategy.